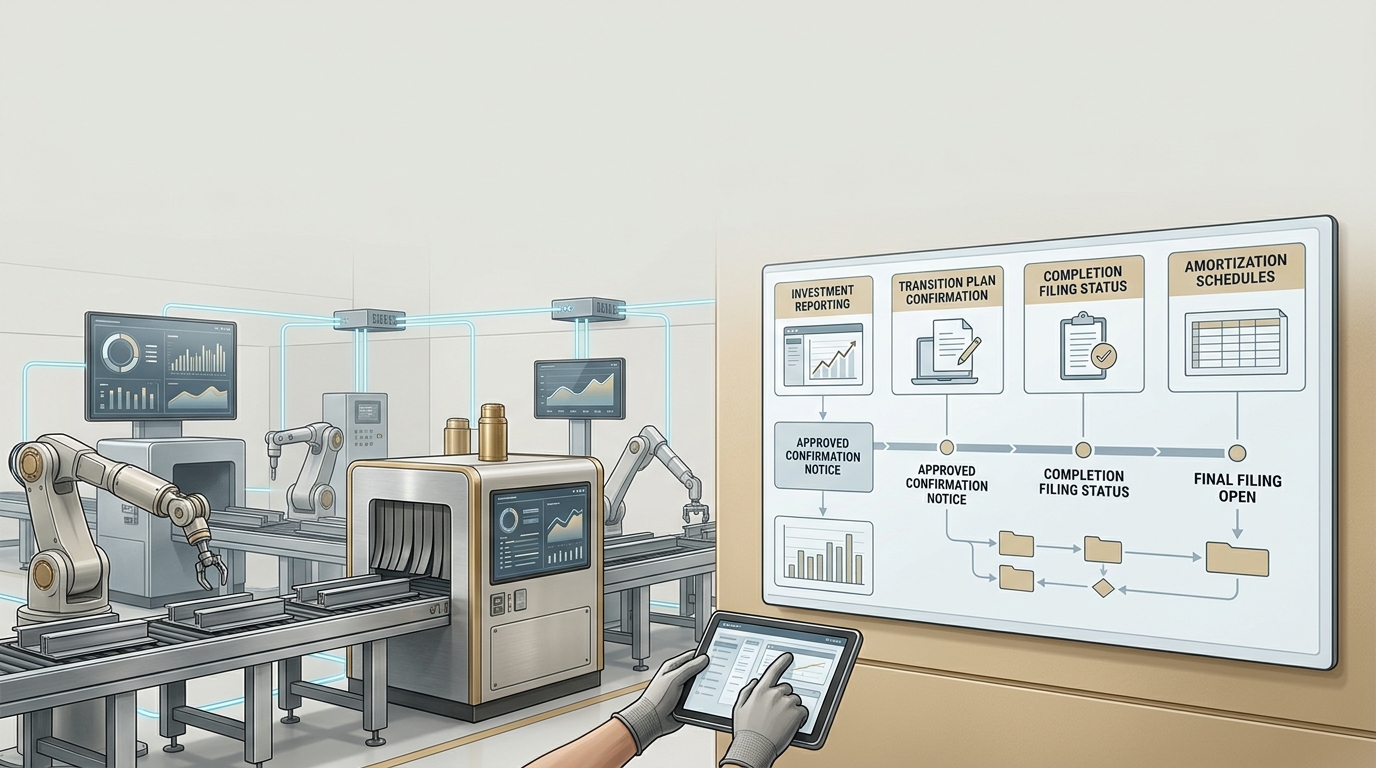
From 12:00 on 15 October 2026, companies can submit completion notices to GSE for investments under the New Transition 5.0 Plan, described in the source text as the 2026-2028 super-depreciation scheme. This activates the third and final stage of the access procedure, following the launch of preliminary notices on 12 June and confirmation notices on 21 July.
The new function was opened by a director's decree dated 14 October 2026 from Italy's Ministry of Enterprises and Made in Italy, implementing the interministerial decree of 7 May. Filings must be submitted through the GSE digital platform, accessed via the GSE customer area, using the forms and operating instructions made available by the agency.
The procedure is limited to companies that have already received a positive outcome on the investment confirmation notice and have completed the eligible investments. For tangible and intangible assets included in Annexes IV and V to the 2026 Budget Law, the notice can be filed only after the investment has been completed and the asset has been interconnected to the company's production management system or supply network. Among other details, the filing must include invoice references for eligible expenses and the completion date for each asset.
Companies must also declare that they hold two key documents: the sworn technical appraisal required under Article 6 of the implementing decree, and the accounting certification required under Article 7. The technical appraisal confirms compliance with the required technological criteria and, where applicable, interconnection. The accounting certification confirms that eligible costs were actually incurred and match the company's accounting records. These documents must be retained for possible inspections.
The system allows one or more completion notices, including notices covering only part of the assets already listed in the earlier confirmation filing. That gives companies more flexibility in multi-stage investment programs where machines, systems or software are completed and interconnected at different times. However, completion notices cannot introduce different assets or amounts above those already stated in the confirmation notice, so reductions are allowed but increases or substitutions are not.
The completion notice must be filed once the investments are finished and in any case by 15 November 2028. The source text states that eligible investments are those made between 1 January 2026 and 30 September 2028. It also states that the implementing decree provides a 20-day extension to the 15 November 2028 deadline if GSE requests additional documentation. After submission, the platform issues a receipt, and GSE has ten days to check whether the uploaded data and information are complete, with a further review cycle if additional documents are requested.
This final filing stage also matters for tax timing. According to the source text, the increased acquisition cost counts for income tax purposes starting from the tax period in which the company submits the completion notice, provided the asset enters into operation within the same tax period. Actual use of the incentive still depends on a positive outcome from GSE's checks. Unlike previous Transition 4.0 and 5.0 tax credits, the new scheme does not use an F24-offsettable tax credit, but rather an increase in the tax-deductible cost through depreciation or lease payments, with uplift rates of 180% up to EUR 2.5 million, 100% between EUR 2.5 million and EUR 10 million, and 50% between EUR 10 million and EUR 20 million.